In December 2025, the retail penetration rate of new energy passenger vehicles exceeded 60% for the first time, accounting for 51.6% of new car sales in October, officially making new energy vehicles the dominant force in the market. The penetration rate of domestic brands reached 79.6%, with BYD surpassing Tesla to become the world’s number one with a 15.7% global pure electric vehicle market share. Meanwhile, the ten-year policy of exempting new energy vehicle purchase tax officially ended on December 31st, and will be adjusted to a 50% reduction starting in 2026, marking a shift in the market from “policy-driven” to “product-driven.”
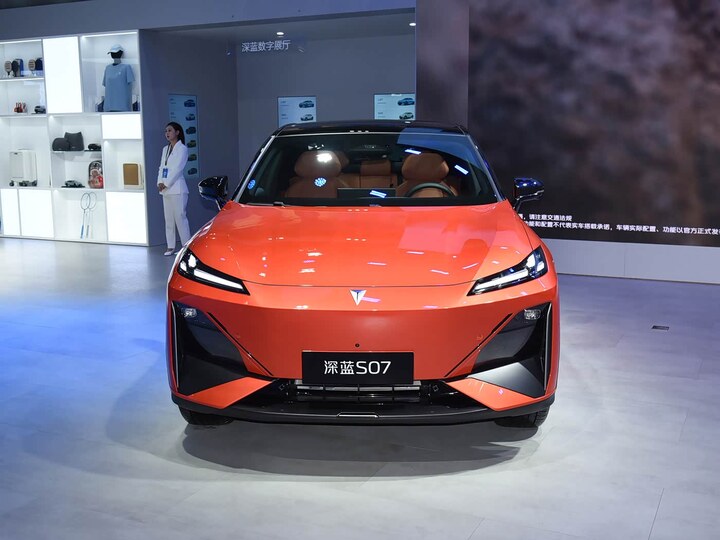
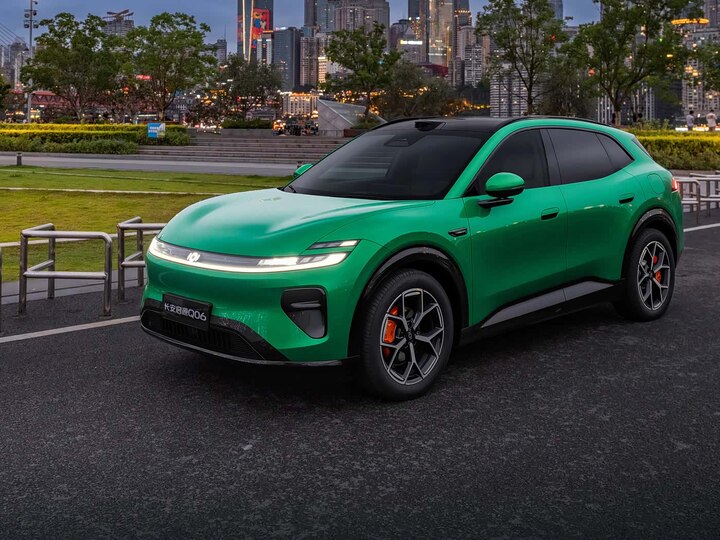
Level 3 (L3) officially launched: On December 15th, the Ministry of Industry and Information Technology (MIIT) announced the first batch of L3-level conditional autonomous driving vehicle mass production access approvals, with Changan Deep Blue and BAIC Jifou receiving approval, enabling legal hands-free driving on designated roads. This marks a new stage in China’s autonomous driving industry, moving from technology verification to mass production and application.
The popularization of intelligent driving: Level 2 assisted driving functions have been extended to vehicles priced around 100,000 rmb, with a penetration rate of 64% in the first three quarters. Intelligent driving is transforming from an “exotic option” to a “basic necessity for car buyers”.